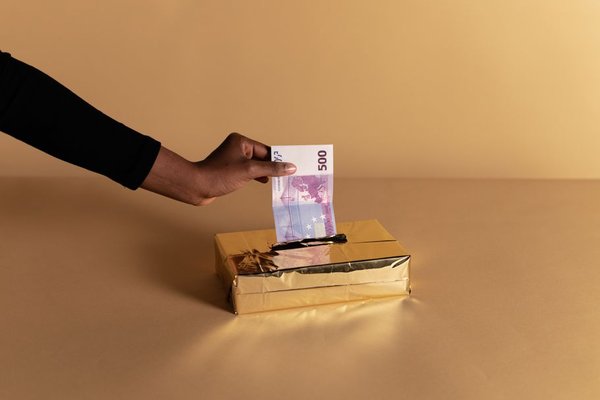
A supplier offers to pay for a weekend away just before you decide who wins a contract. A sales agent says an unofficial cash payment will get goods through customs faster. For a small UK business, moments like these can create serious legal exposure, even when nobody calls the arrangement a bribe.
The Bribery Act 2010 applies to businesses of all sizes. Bribery Act compliance for small businesses in the UK does not necessarily mean hiring a compliance department. It means recognising where improper influence could enter ordinary transactions and putting sensible safeguards in place.
What does the Bribery Act cover?
The Act creates offences involving offering or giving a bribe, requesting or accepting one, and bribing a foreign public official to obtain or retain business or a business advantage. A bribe can involve money, gifts, hospitality or another benefit. What matters is the circumstances and the improper influence involved, not simply the label on an expense claim.
Bribery is not limited to public officials. A private-sector purchasing manager who accepts a benefit in exchange for favouring a supplier can also raise concerns. UK-connected individuals and companies may face liability for relevant conduct overseas, so a payment being customary in another country is not a reliable defence.
The corporate bribery offence matters to smaller firms
Section 7 creates a separate offence where a commercial organisation fails to prevent an associated person from bribing another person intending to obtain or retain business or a business advantage for that organisation. There is no general small-business exemption.
An associated person is someone performing services for or on behalf of the business. Employees and agents are obvious examples; contractors and intermediaries may qualify depending on what they actually do. Not every supplier automatically falls into this category.
For this section 7 offence, an organisation has a defence if it can prove that it had adequate procedures designed to prevent such bribery. Those procedures must suit the actual risks. The defence does not erase an individual’s separate bribery offence.
Where a small business is most exposed
Gifts and hospitality
Ordinary business lunches and reasonable promotional hospitality are not automatically unlawful. There is no universal legal monetary threshold below which every gift is safe. Instead, consider its value, timing, purpose and recipient.
A modest lunch after a routine meeting looks different from an expensive holiday offered to the person deciding a tender. Keep a simple gifts and hospitality register recording who gave or received the benefit, its approximate value, the business reason and who approved it. Require advance approval for anything unusual or connected to a live procurement decision.
Agents, introducers and overseas partners
Third parties can create risks that are easy to miss. A consultant promising guaranteed permits, requesting unexplained commissions or insisting on payment to a personal account deserves scrutiny. Ask what services will be performed, check the person’s background, document the fee and require legitimate invoices.
If an overseas official requests a small unofficial payment to perform a routine duty, that is often called a facilitation payment. UK law does not provide a general exemption for these payments. Staff should know how to refuse, record and escalate requests, particularly where personal safety is involved.
Build anti-bribery procedures that fit your business
The Ministry of Justice describes six principles: proportionate procedures, top-level commitment, risk assessment, due diligence, communication and training, and monitoring and review. They are a framework, not a demand for identical paperwork from every business.
Start with a short risk assessment
Identify who can approve spending, award work, negotiate with public bodies or appoint overseas representatives. Consider the countries and sectors involved, contract values and use of intermediaries. A local design studio may have fewer risks than a small exporter relying on customs agents. Record the conclusions and revisit them when the business changes.
Make the rules usable
A concise policy can forbid bribes and facilitation payments, explain approval rules for gifts, set checks for agents and identify someone staff can contact confidentially. Support it with straightforward bookkeeping: keep receipts, separate payment approval from reconciliation where practical, and reject vague descriptions such as “special services”.
Owners should demonstrate that sales targets never excuse improper payments. Explain the policy when someone joins, give short refresher training to higher-risk staff and ensure external representatives understand the expectations. For related governance guidance, see business compliance checklist and conflicts of interest policy when planning your internal resources.
Review evidence, not just documents
Check a sample of expenses and agent payments periodically. Ask whether approvals happened before hospitality was offered, whether unusual commissions were challenged and whether reported concerns were resolved. Update controls after entering a new market or finding a weakness. A signed policy that nobody follows offers limited protection.
A practical example: the sales commission warning sign
Imagine a five-person engineering company bidding for work overseas. A local intermediary asks for a 20% success fee and says the company must not ask how relationships with officials are managed. Rather than signing immediately, the owner requests a written scope of work, verifies the intermediary’s identity and track record, assesses the proposed fee and requires contract terms prohibiting bribery.
If the intermediary refuses reasonable checks, the company can decline the arrangement. Recording that decision is useful evidence that the business takes third-party risks seriously. This kind of targeted due diligence is more valuable than copying a lengthy policy that does not address the deal.
What if you suspect a bribe?
Stop any questionable payment you control, preserve relevant records and report the concern promptly to the nominated owner or adviser. Avoid conducting an improvised investigation that could compromise evidence. Serious concerns may warrant specialist legal advice and appropriate reporting to authorities. Have a clear, confidential route for employees to speak up without retaliation.
Potential consequences are substantial: individuals convicted of the main bribery offences can face imprisonment of up to ten years and/or an unlimited fine on indictment, while organisations can face unlimited fines. Reputational damage and lost contracts may follow too.
Frequently asked questions
Does the Bribery Act apply to sole traders?
Yes. Individuals can commit the general bribery offences. The section 7 failure-to-prevent offence specifically concerns relevant commercial organisations, including companies and partnerships, rather than every sole trader acting alone.
Must every small company have a written anti-bribery policy?
The Act does not prescribe one standard written policy for every firm. Risk-appropriate procedures matter, especially if a business needs to establish the section 7 defence. Simple documented rules can make expectations easier to demonstrate.
Are client gifts always prohibited?
No. Genuine, reasonable gifts and hospitality are not automatically bribes. Their purpose, scale, timing and surrounding circumstances determine the risk. Transparency and approval help.
Can we be liable for an agent’s actions abroad?
Potentially. If the agent performs services for your organisation and bribes to win or retain business for it, section 7 may apply. Risk-based due diligence and meaningful oversight are important.
Conclusion
Effective anti-bribery compliance is about decisions, not document volume. Know who represents your business, question suspicious payments, keep proportionate records and make it easy for staff to raise concerns. Connect this work with your small business risk management practices and review safeguards as your operations grow.